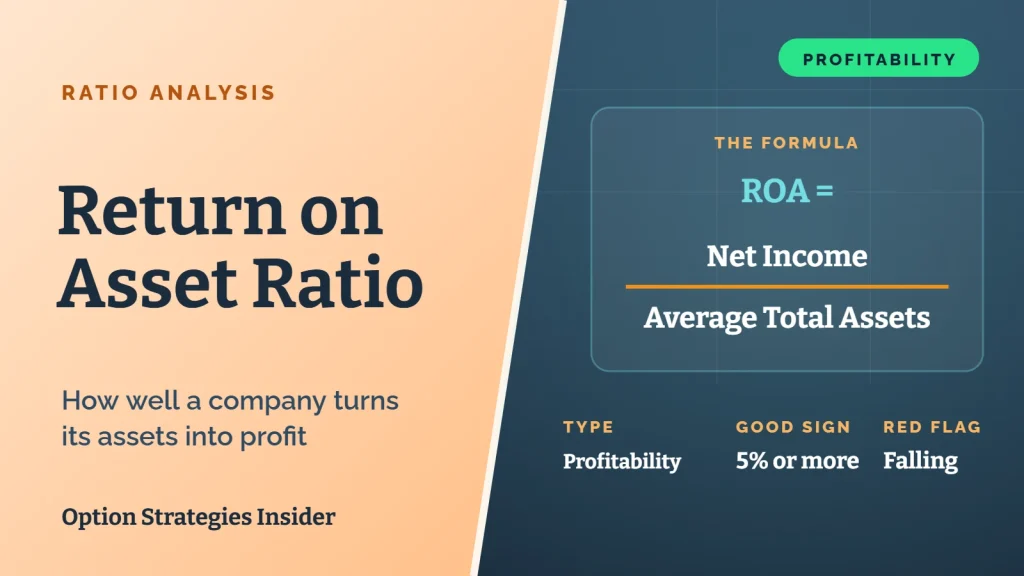
The return on assets ratio (ROA), also referred to as the return on total assets, is a productivity ratio measuring the net income made by a company’s total assets at a given time frame. In short, the ROA or the return on assets measures how a company’s assets can be managed to gain profit over a given period.
The return on assets ratio is given as a percentage. The higher the percentage, the more effective a company’s management is in generating profits by managing its balance sheet. Since the purpose of a company’s assets is to generate revenue, the ratio is useful to both the investors and the management in gauging how well the company can generate profits from its investments in assets.
ROA can also be considered a return on investment as most companies’ most significant investments are informed from capital intensive assets. Thus, companies invest in capital assets, and the gains are quantified as profits. Therefore, ROA measures the profitability of a company’s assets.
The ROA Formula
Return on investment is calculated by taking the business’s net income and dividing it by its total assets. The net income is the amount that the business is left with after deducting all the business expenses. Net income (or loss) can be found at the bottom of the income statement. The total average assets are contained in the business balance sheet. The formula for calculating ROA is:
Return on Assets (ROA) = Net Income / Average Total Assets
Example
Let’s take the example of two companies.
Company A has a net income of $6.3 million in 2019 and $3.6 million in 2018. Total assets from the balance sheet read $70 million in 2019 and $60 million in 2018.
Return on assets for company A = 6.3 / 70
= 9% in 2019
Return on assets for company A = 3.6/60
=6% in 2018
From the above example, it is concluded that the company’s management is doing well at managing its assets to make a profit. That is because the ROA was 9% in 2019 and 6% in 2018. A high return on assets is a good indicator.
Characteristics of a Good Return on Asset Ratio
A good return on assets ratio shows that a company is effective in the management of its assets. A company with a good ROA should be within the range of its peer companies. If an industry has an average ROA of 15% and a company has a ROA of 15.7, it is assumed to manage its assets well in relation to the industry.
However, if a company has a ROA that is much higher than the average of its peer companies, for example, 20% compared to the average 15%, it could mean either of two scenarios.
The company does not own many assets. Instead, they borrow or lease extra assets. ROA takes into account only the assets owned. Companies with fewer assets have a high ROA. The company can manage its assets better to gain more income. Management and earnings capabilities are essential factors, as well as the method used by companies to finance their assets.
Importance of ROA
It is important to measure a company’s profitability. This shows how well a company utilizes assets to make a profit. The ratio is mostly used when comparing two peer companies of the same size in a similar industry or a company’s performance between different times. They are used internally to trace the use of assets over time, look into the company’s performance concerning their industry, or compare two different divisions or operations. ROA can tell if assets are under-utilized or if they are effectively used to generate profit.
The ROA ratio can also be used internally to evaluate the benefits of expanding an existing operation or investing in a new system. The best choice should increase income and productivity and reduce assets’ cost.
ROA vs ROE
Both ROE and ROA are financial ratios central in investing. These profitability ratios are used to measure a company’s performance. Return on equity (ROE) helps traders understand how a company’s ventures generate profit, while return on assets (ROA) helps traders measure how management is putting a company’s assets and other resources to work to create cash flow.
ROA vs Asset Turnover Ratio
The main difference between the return on assets ratio and asset turnover ratio is that the return on assets takes into account net income and asset turnover concentrates on revenues. Using net income instead of revenues, the return on assets formula also factors in a firm’s expenses.
How Asset Turnover and ROA Connect
Asset turnover and return on assets are closely linked. Asset turnover measures how much revenue a company generates from its assets. ROA measures how much profit it generates from those assets. You can connect them with this formula:
ROA = net profit margin x asset turnover
If a company has a 10% net profit margin and an asset turnover of 1.5, its ROA is 10% x 1.5, or 15%. A grocery chain might have thin margins but very high turnover, while a software company might have high margins and low turnover. Both can end up with a strong ROA in different ways.
Cash Return on Assets
Cash return on assets swaps net income for operating cash flow. The formula is operating cash flow divided by total assets. Because cash flow is harder to adjust with accounting choices than net income, some investors use it as a check on regular ROA. If a company’s ROA looks strong but its cash return on assets is much weaker, it’s worth digging into why.
Limitation of ROA
ROA cannot be used to compare companies across industries. Companies in different sectors have diverse asset footings. For instance, a technology company will own software, whereas manufacturing companies will hold many more assets such as shipping containers and warehouses.
All internal and external factors should be included, and consider the competitors, ROA of industry, and market demand while analyzing and interpreting using ROA. Other internal factors that have a significant impact on ROA include changing and replacing the accounting policies and using old assets.
Return on Assets FAQ
Is return on assets the same as asset turnover? No. Asset turnover divides revenue by assets, so it measures how much a company sells. ROA divides net income by assets, so it measures how much the company keeps as profit. ROA equals asset turnover times net profit margin, which is why the two tend to move together.
What is a good return on assets? As a rough guide, above 5% is solid and above 10% is strong. Banks often run around 1% and utilities 2% to 4% because they carry huge balance sheets, while asset-light software companies can top 15%. Always compare a company to its own industry.
Is ROA just net income over total assets? Yes, that’s the basic version: net income divided by average total assets. Some analysts add back after-tax interest expense so a company’s debt load doesn’t distort the result.
What’s the difference between ROA and return on total assets? Some sources use return on total assets (ROTA) to mean EBIT divided by total assets, which leaves out interest and taxes. Others treat it as just another name for ROA. Check which formula a screener uses before you compare numbers.
Can ROA be negative? Yes. If a company loses money, net income is negative and so is ROA. One bad year isn’t a red flag by itself, but several in a row usually is.
Return on assets shows how well management uses what the company owns. To learn how to act on that research with options, check out our beginner’s options trading course.
Related Financial Ratios
- Return on Equity: how well it uses shareholder money
- Asset Turnover: sales from each $1 of assets
- Net Profit Margin: profit after every expense
- All 28 Financial Ratios: the full guide, grouped by type