The debt-to-income ratio (DTI) is a tool that relates recurring monthly debt of an individual to their overall gross income. In this case, the gross income is the revenue before the taxes and other deductions. It means the debt to income can be construed as the gross monthly income percentage, which goes toward paying the monthly debt payments. Usually, creditors consider the consumers with high debt to ratio as the riskier options because these customers may have problems with repaying the loan, especially if there are financial issues to solve.
Formula
The formula to calculate your debt-to-income ratio is as follows:
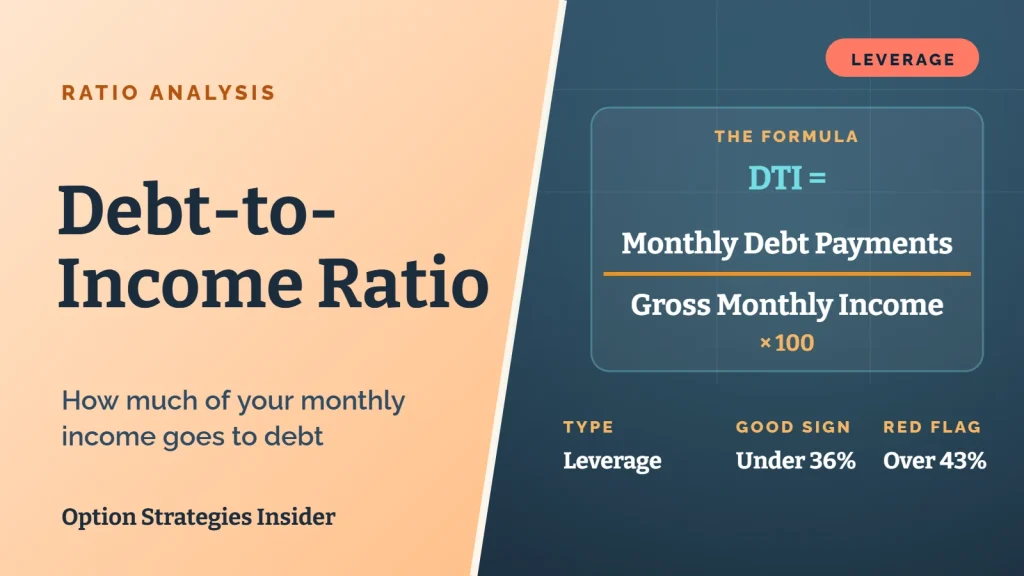
Debt-to-Income Ratio = Total Monthly Payments or Debts / Gross Monthly Income
When calculating calculating your DTI, if the ratio is low, it shows a good balance between the income and the debt levels. If the ratio is 15%, for example, 15% of the monthly income is redirected towards the debts every month. On the other hand, a high debt to ratio would signal that the individual has too much debt for their income monthly.
The ideal Debt-to-Income and how it Impacts Credit
Lenders prefer a front end ratio that does not exceed 28%, and the backend should be 36% and lower. Depending on one’s credit report, down payments, and the assets available, the lenders may decide to accept a higher ratio depending on the loan which is being applied. For the conventional loans from Freddie Mac and Fannie Mae, the lenders would accept debt-to-income ratios as high as 50%. It means half of the returns or income attained is going toward the rent or other monthly debt obligations.
Does the debt-to-income affect the Credit
Financial institutions do not consider the individual’s income when they score the credit meaning the debt-to-income does not have a large bearing on the score. However, the borrowers with a big debt-to-income ratio would have a large credit utility ratio, meaning above 30% of the credit score. The credit utility ratio is the outstanding balance for the accounts related to the maximum credit limit. The DTI ratio is one of the debt ratios that lenders prefer. This includes qualified mortgage, car loans, or applying for homeowner insurance.
Should the credit card have a limit of $3000 and the balance is $1500, then the credit utility ratio would be 50%. Ideally, one would want to keep the ratio beneath 30% when placing an application with mortgage lenders or applying for a mortgage. Decreasing the credit utility ratio will boost the level of the credit score and reduce the debt-to-income because one is paying down more of the debt.
How to Reduce the Debt-to-Income Ratio
- Mapping a plan for the debts- two great means of tackling the debt include the snowball or avalanche approaches. The snowball theme means paying down a small credit balance but also making minimum payments for the others. Once the minimum balance is paid, one moves to the other in the hierarchy. The avalanche approach means doing the accounts according to high-interest rates. Once the balance has been paid, if it has a high-interest rate, one moves on to the next with the second-highest rate and so forth. Regardless of the direction chosen, the objective is to stick to the plan.
- Making the debt more affordable- if there are high-interest credit cards, consider ways to lower the interest. It would be advisable to call the credit card firm and see if it is possible to lower the interest rates. There may be more success with that path if the account is in good standing and there is no delinquency with the bills.
Debt-to-Income Ratio Example
Say your monthly debt payments add up to $2,000: a $1,400 mortgage, a $400 car loan and $200 in minimum credit card payments. Your gross monthly income, before taxes, is $6,000. Your debt-to-income ratio is $2,000 divided by $6,000, or about 33%.
Front-End vs. Back-End DTI
Mortgage lenders often look at two versions. Front-end DTI only counts housing costs, like your mortgage, property taxes and insurance. Back-end DTI counts all of your monthly debt payments. Many lenders like to see back-end DTI at 36% or less, though some loan programs allow higher ratios, often up to around 43% to 50%, depending on the rest of your application.
Debt-to-Income vs. Debt-to-Equity
Debt-to-income is a personal finance ratio that lenders use to judge whether you can afford a loan. The debt-to-equity ratio is a company ratio investors use to measure how much a business relies on borrowing. They both measure debt, just for very different purposes.
Debt-to-Income FAQ
How do you calculate debt-to-income? Add up your monthly debt payments and divide by your gross monthly income, then multiply by 100 to get a percentage.
Does DTI include rent or utilities? Rent is often included when lenders look at your current obligations, but utilities, groceries and other living costs usually aren’t.
Where can I learn more ratios? See our guide to the 5 types of financial ratios.
Disadvantages of Debt-to-Income
Even though the debt-to-income may be significant, it is only a sole financial ratio for making business decisions. The credit history of the one who is borrowing will also weigh on the decisions to extend credit from the investors. A credit score represents a numeric value of past performance when it comes to paying bills and debts.
Different factors affect the score, such as late mortgage payments and defaults. The borrower may also have balances on their credit cards, which show they are not good with obligations, but it may not have anything to do with that particular loan.
The debt-to-income does not necessarily differentiate between debts. Credit card payments also have higher interest rates than student loans, personal loans, or auto loans, though they are lumped together within the calculation. That does not give an accurate illustration of the owner’s ability to pay obligations.
Knowing your debt-to-income ratio is a smart first step toward investing. When you’re ready to learn options from the ground up, start with our free options trading course.
Related Financial Ratios
- Debt-to-Equity Ratio: debt compared to shareholder equity
- Debt Ratio: the share of assets paid for with debt
- Interest Coverage Ratio: can profits cover the interest bill
- All 28 Financial Ratios: the full guide, grouped by type